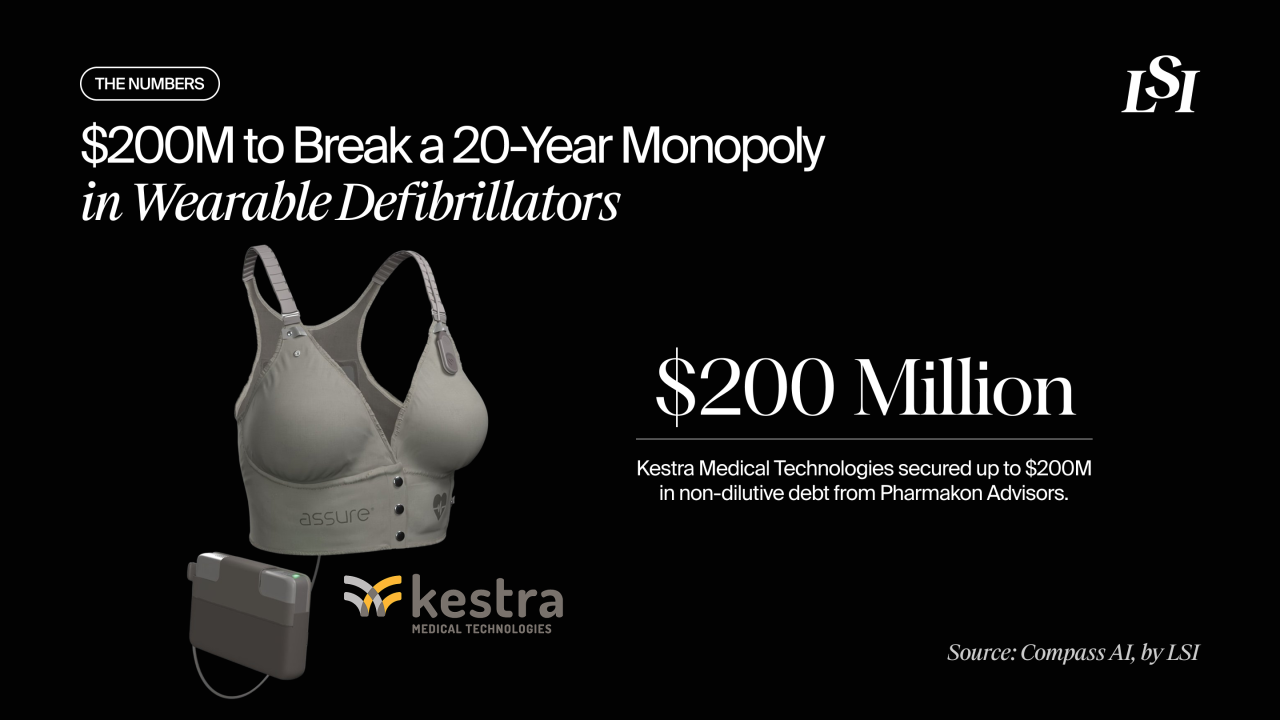
On July 14, Kestra Medical Technologies announced two significant milestones. The company reported $95.1 million in fiscal 2026 revenue, representing 59% year-over-year growth, and secured up to $200 million in non-dilutive financing from Pharmakon Advisors.
Those announcements represent more than another successful financing. They suggest one of the fastest-growing companies in the wearable defibrillator market now has the resources to challenge one of medtech’s longest-standing competitive positions.
For nearly two decades, ZOLL’s LifeVest has dominated the wearable cardioverter defibrillator (WCD) category. Kestra’s accelerating commercial performance, combined with substantial non-dilutive capital, signals that the market may finally be entering a new phase.
The Wearable Defibrillator Market Is Becoming Competitive
Wearable cardioverter defibrillators provide temporary protection for patients at elevated risk of sudden cardiac death. Patients recovering from a heart attack or newly diagnosed with cardiomyopathy often wear these devices while physicians determine whether permanent therapy is necessary.
For years, the category remained largely unchanged.
The global WCD market is valued at approximately $298 million in 2026 and is projected to reach $535 million to $583 million by 2033. ZOLL’s LifeVest accounts for roughly 45% of global revenue and has operated with limited direct competition in the United States throughout most of its history.
Kestra’s ASSURE system is emerging as the strongest challenger. During fiscal 2026, the company reported 59% revenue growth, 57% growth in ASSURE prescriptions to 20,720, gross margin expansion from 40.5% to 51.4%, and its tenth consecutive quarter of margin improvement. The company also guided to approximately $137 million in revenue for the coming fiscal year.
Historically, broader adoption of WCDs has been constrained by two factors: garments that many patients found difficult to wear consistently and ongoing debate surrounding clinical effectiveness. Both dynamics are beginning to shift as new products enter the market.
Why Wearability Has Become the Defining Competitive Advantage
A wearable defibrillator can only deliver therapy if the patient is wearing it when a life-threatening arrhythmia occurs. Compliance is not simply an operational metric; it directly determines whether the technology can save a life.
That reality has made wearability the primary battleground.
Kestra’s ASSURE system is approximately 30% lighter than conventional garments and has gained traction among pediatric and active patients.
Element Science has taken an even different approach. Its FDA-approved Jewel system replaces the traditional vest with an adhesive patch and achieved median wear times exceeding 23 hours per day during its pivotal clinical trial.
After two decades of relatively limited innovation, the WCD market is finally competing on the characteristic that matters most: whether patients will consistently wear the device.
Why Kestra Chose Debt Instead of Equity
Kestra’s financing consists of a five-year senior secured term loan providing $75 million at closing, which was used in part to retire the company’s existing $45 million term loan. Additional tranches of $25 million and $50 million are available at Kestra’s option, with the larger tranche becoming available once the company reaches $150 million in trailing twelve-month revenue. The agreement also includes a separate $50 million uncommitted acquisition tranche, subject to Pharmakon’s approval, while providing 48 months of interest-only payments.
For a company growing revenue by 59% while continuing to expand margins, non-dilutive debt allows management to fund growth without issuing additional equity. The structure also reflects a broader trend LSI has highlighted in recent months, with several of medtech’s largest financings favoring debt over equity as companies preserve shareholder value while public market multiples remain compressed.
LSI’s Perspective
This announcement reinforces two themes that continue to shape medtech.
The first is the strength of incumbent market leaders. ZOLL has spent decades building the WCD category, and its fifth-generation LifeVest reports a 97% first-shock success rate. Market leadership of that scale is difficult to disrupt.
The second is the importance of well-capitalized challengers. A differentiated product alone rarely changes an established market. Combining a differentiated product with significant financial resources creates a much more credible competitive threat.
The most meaningful outcome, however, may benefit the category as a whole. If more comfortable devices improve patient compliance, stronger outcomes data could encourage broader physician adoption and expand the overall market rather than simply shifting share between competitors.
Compass AI’s Predictions
Compass AI’s Prediction Agent (a Beta capability) fuses LSI's proprietary intelligence (i.e., the millions of data points across our library of executive talks, interviews, research, and editorial content) with the live company and deal data in our database.
Here’s what our Agent predicts:
- Element Science becomes an acquisition target. Compass AI believes a major cardiac rhythm management company, such as Boston Scientific, Medtronic, or Abbott, could acquire Element Science within the next 18 months as the wearable defibrillator market becomes increasingly competitive.
- ZOLL responds aggressively. Expect the market leader to answer with a lighter device, a patch-style alternative, more aggressive pricing, or a combination of those strategies as new competitors gain momentum.
- Kestra expands beyond WCDs. The financing’s dedicated acquisition tranche suggests the company intends to build a broader cardiac monitoring and therapy platform rather than remain a single-product company.
Final Thoughts
Kestra’s financing is about more than strengthening its balance sheet. It provides one of the industry’s fastest-growing challengers with the resources to compete in a category that has seen little meaningful competition for two decades. If improved product design increases patient compliance and strengthens clinical evidence, the biggest winner may ultimately be the wearable defibrillator market itself, with broader adoption creating a larger opportunity for every participant.

Request Info

The Lens - Complimentary Issue
Subscription Includes

Global Medtech Market Analysis & Projections (MAP), 2021-2031
Published: 2023
Next Update: Q4 2024
Deliverables:


Global Surgical Procedure Volumes Dashboard, 2018-2029
Published: 2022
Next Update: Q2 2024
Deliverables:
United States Surgical Procedure Volumes, 2018-2029
Published: 2022
Next Update: Q2 2024
Deliverables:
Aesthetics, Global Surgical Procedure Volumes, 2018-2029
Published: 2022
Next Update: Q2 2024
Deliverables:
Cardio, Global Surgical Procedure Volumes, 2018-2029
Published: 2022
Next Update: Q2 2024
Deliverables:
ENT, Global Surgical Procedure Volumes, 2018-2029
Published: 2022
Next Update: Q2 2024
Deliverables:
General, Global Surgical Procedure Volumes, 2018-2029
Published: 2022
Next Update: Q2 2024
Deliverables:
Neuro, Global Surgical Procedure Volumes, 2018-2029
Published: 2022
Next Update: Q2 2024
Deliverables:
OB/GYN, Global Surgical Procedure Volumes, 2018-2029
Published: 2022
Next Update: Q2 2024
Deliverables:
Ophthalmology, Global Surgical Procedure Volumes, 2018-2029
Published: 2022
Next Update: Q2 2024
Deliverables:
Orthopedic, Global Surgical Procedure Volumes, 2018-2029
Published: 2022
Next Update: Q2 2024
Deliverables:
Peripheral Vascular, Global Surgical Procedure Volumes, 2018-2029
Published: 2022
Next Update: Q2 2024
Deliverables:
Spine, Global Surgical Procedure Volumes, 2018-2029
Published: 2022
Next Update: Q2 2024
Deliverables:
SRS, Global Surgical Procedure Volumes, 2018-2029
Published: 2022
Next Update: Q2 2024
Deliverables:
Urological, Global Surgical Procedure Volumes, 2018-2029
Published: 2022
Next Update: Q2 2024
Deliverables:
Global Markets for Hip Replacement Implants, 2023-2028
Published: 2023
Next Update: Q2 2024
Deliverables:
Global Markets for Peripheral Vascular Guidewires, 2023-2028
Published: 2023
Next Update: Q2 2024
Deliverables:
Global Markets for Peripheral Atherectomy Catheters, 2023-2028
Published: 2023
Next Update: Q2 2024
Deliverables:
Global Markets for Electrosurgery, 2023-2028
Published: 2023
Next Update: Q2 2024
Deliverables:
Global Markets for Peripheral Vascular Balloons & Vena Cava Filter, 2023-2028
Published: 2023
Next Update: Q2 2024
Deliverables:
Global Markets for Mechanical Heart Valves, 2023-2028
Published: 2023
Next Update: Q2 2024
Deliverables:
Global Markets for Tissue Heart Valve Replacement, 2023-2028
Published: 2023
Next Update: Q2 2030
Deliverables:
Global Markets for Transcatheter Mitral Valve Devices, 2023-2028
Published: 2023
Next Update: Q2 2024
Deliverables:
Global Markets for Femoral Closure, 2023-2029
Published: 2023
Next Update: Q2 2024
Deliverables:
Global Markets for Tricuspid Valve Repair, 2023-2028
Published: 2023
Next Update: Q2 2024
Deliverables:
Global Markets for Percutaneous Pulmonary Valves, 2023-2028
Published: 2023
Next Update: Q2 2024
Deliverables:
Global Markets for Coronary Angio Guidewires & Catheters, 2023-2028
Published: 2023
Next Update: Q2 2024
Deliverables:
Global Markets for Oncology Ablation Devices, 2023-2028
Published: 2023
Next Update: Q2 2024
Deliverables:
Global Markets for ENT Devices, 2023-2028
Published: 2023
Next Update: Q2 2024
Deliverables:
Global Markets for Cell Delivery Catheters, 2023-2028
Published: 2023
Next Update: Q3 2024
Deliverables:
Global Markets for Urology Devices, 2023-2028
Published: 2023
Next Update: Q3 2024
Deliverables:
Global Markets for External Pain Pumps, 2023-2028
Published: 2023
Next Update: Q3 2024
Deliverables:
Global Markets for Ureteral Access Devices, 2023-2028
Published: 2023
Next Update: Q3 2024
Deliverables:
Global Markets for Pelvic Floor Repair, 2023-2028
Published: 2023
Next Update: Q3 2024
Deliverables:
Global Markets for Atrial Fibrillation, 2023-2028
Published: 2023
Next Update: Q3 2024
Deliverables:
Global Markets for Neurovascular Devices Ischemic, 2023-2028
Published: 2023
Next Update: Q3 2024
Deliverables:
Global Markets for Neuromodulation Devices, 2023-2028
Published: 2023
Next Update: Q3 2024
Deliverables:
Global Markets for Vertebroplasty Devices, 2023-2028
Published: 2023
Next Update: Q3 2024
Deliverables:
Global Markets for Benign Prostation Hyperplasia Implants, 2023-2028
Published: 2023
Next Update: Q3 2024
Deliverables:
Global Markets for Cryoablation, 2023-2028
Published: 2023
Next Update: Q3 2024
Deliverables:
Global Markets for Diagnostic Electrophysiology Catheters, 2023-2028
Published: 2023
Next Update: Q3 2024
Deliverables:
Global Markets for Hernia Repair, 2023-2028
Published: 2023
Next Update: Q4 2024
Deliverables:
Global Markets for CRM Devices, 2023-2028
Published: 2023
Next Update: Q4 2024
Deliverables:
Global Markets for Neurovascular Devices Hemorrhagic, 2023-2028
Published: 2023
Next Update: Q4 2024
Deliverables:
Global Markets for Renal Denervation, 2023-2028
Published: 2023
Next Update: Q4 2024
Deliverables:
Global Markets for Upper+Lower Suture Anchors, 2023-2028
Published: 2023
Next Update: Q4 2024
Deliverables:
Global Markets for Peripheral Stents, 2023-2028
Published: 2023
Next Update: Q4 2024
Deliverables:
Global Markets for Electromagnetic Navigation Systems, 2023-2028
Published: 2023
Next Update: Q4 2024
Deliverables:
Global Markets for GI Endoscopy, 2023-2028
Published: 2023
Next Update: Q4 2024
Deliverables:
Global Markets for Hemodialysis, 2023-2028
Published: 2023
Next Update: Q4 2024
Deliverables:
Globals Markets for Cardiac Ablation, 2023-2028
Published:
Next Update:
Deliverables:
Global Markets for Atrial Septal Occlusion, 2023-2028
Published: 2023
Next Update: Q4 2024
Deliverables:
Global Markets for Aortic Grafts, 2023-2028
Published: 2023
Next Update: Q4 2024
Deliverables:
Global Markets for Interventional Cardiology Devices, 2023-2028
Published: 2023
Next Update: Q4 2024
Deliverables:
Global Markets for Oncology Embolization, 2023-2028
Published: 2023
Next Update: Q4 2024
Deliverables:
Global Markets for Vascular Access Devices, 2023-2028
Published: 2023
Next Update: Q4 2024
Deliverables:
Global Markets for Rotator Cuff Repair Suture Anchors, 2023-2028
Published: 2023
Next Update: Q4 2024
Deliverables:
Global Markets for Electrical Stimulation Devices, 2023-2028
Published: 2023
Next Update: Q4 2024
Deliverables:
Global Markets for Wearable Monitoring Devices, 2023-2028
Published: 2023
Next Update: Q4 2024
Deliverables:
Global Markets for Low Complexity Medical Devices, 2023-2028
Published: 2023
Next Update: Q4 2024
Deliverables:
Canada Surgical Procedure Volumes, 2018-2029
Published: 2022
Next Update: Q2 2024
Deliverables:
Germany Surgical Procedure Volumes, 2018-2029
Published: 2022
Next Update: Q2 2024
Deliverables:
France Surgical Procedure Volumes, 2018-2029
Published: 2022
Next Update: Q2 2024
Deliverables:
U.K. Surgical Procedure Volumes, 2018-2029
Published: 2022
Next Update: Q2 2024
Deliverables:
Italy Surgical Procedure Volumes, 2018-2029
Published: 2022
Next Update: Q2 2024
Deliverables:
Spain Surgical Procedure Volumes, 2018-2029
Published: 2022
Next Update: Q2 2024
Deliverables:
Poland Surgical Procedure Volumes, 2018-2029
Published: 2022
Next Update: Q2 2024
Deliverables:
Netherlands Surgical Procedure Volumes, 2018-2029
Published: 2022
Next Update: Q2 2024
Deliverables:
Belgium Surgical Procedure Volumes, 2018-2029
Published: 2022
Next Update: Q2 2024
Deliverables:
Sweden Surgical Procedure Volumes, 2018-2029
Published: 2022
Next Update: Q2 2024
Deliverables:
Switzerland Surgical Procedure Volumes, 2018-2029
Published: 2022
Next Update: Q2 2024
Deliverables:
Denmark Surgical Procedure Volumes, 2018-2029
Published: 2022
Next Update: Q2 2024
Deliverables:
Finland Surgical Procedure Volumes, 2018-2029
Published: 2022
Next Update: Q2 2024
Deliverables:
Norway Surgical Procedure Volumes, 2018-2029
Published: 2022
Next Update: Q2 2024
Deliverables:
China Surgical Procedure Volumes, 2018-2029
Published: 2022
Next Update: Q2 2024
Deliverables:
India Surgical Procedure Volumes, 2018-2029
Published: 2022
Next Update: Q2 2024
Deliverables:
Japan Surgical Procedure Volumes, 2018-2029
Published: 2022
Next Update: Q2 2024
Deliverables:
South Korea Surgical Procedure Volumes, 2018-2029
Published: 2022
Next Update: Q2 2024
Deliverables:
Australia Surgical Procedure Volumes, 2018-2029
Published: 2022
Next Update: Q2 2024
Deliverables:
Thailand Surgical Procedure Volumes, 2018-2029
Published: 2022
Next Update: Q2 2024
Deliverables:
Malaysia Surgical Procedure Volumes, 2018-2029
Published: 2022
Next Update: Q2 2024
Deliverables:
Singapore Surgical Procedure Volumes, 2018-2029
Published: 2022
Next Update: Q2 2024
Deliverables:
New Zealand Surgical Procedure Volumes, 2018-2029
Published: 2022
Next Update: Q2 2024
Deliverables:
Caribbean Surgical Procedure Volumes, 2018-2029
Published: 2022
Next Update: Q2 2024
Deliverables:
Argentina Surgical Procedure Volumes, 2018-2029
Published: 2022
Next Update: Q2 2024
Deliverables:
Colombia Surgical Procedure Volumes, 2018-2029
Published: 2022
Next Update: Q2 2024
Deliverables:
Chile Surgical Procedure Volumes, 2018-2029
Published: 2022
Next Update: Q2 2024
Deliverables:
Guatemala Surgical Procedure Volumes, 2018-2029
Published: 2022
Next Update: Q2 2024
Deliverables:
Dominican Republic Surgical Procedure Volumes, 2018-2029
Published: 2022
Next Update: Q2 2024
Deliverables:
Costa Rica Surgical Procedure Volumes, 2018-2029
Published: 2022
Next Update: Q2 2024
Deliverables:
Panama Surgical Procedure Volumes, 2018-2029
Published: 2022
Next Update: Q2 2024
Deliverables:
Mexico Surgical Procedure Volumes, 2018-2029
Published: 2022
Next Update: Q2 2024
Deliverables:
Brazil Surgical Procedure Volumes, 2018-2029
Published: 2022
Next Update: Q2 2024
Deliverables:
Turkey Surgical Procedure Volumes, 2018-2029
Published: 2022
Next Update: Q2 2024
Deliverables:
Russia Surgical Procedure Volumes, 2018-2029
Published: 2022
Next Update: Q2 2024
Deliverables:
South Africa Surgical Procedure Volumes, 2018-2029
Published: 2022
Next Update: Q2 2024
Deliverables:
Request Info
See Full Attendee List