Olympus is making another move in the prostate market, but this time the strategy looks very different.
On 20 August 2026, MaxQ Medical closed a $31.5 million Series A led by Olympus Innovation Ventures, Atlantic Blue Ventures, and S3 Ventures, with strong participation from existing investor Hillside Capital.
Led by LSI Alumni Amir Tehrani, the Sunnyvale company is developing a single transurethral platform designed to image and treat the prostate in the same procedure. The initial target is BPH treatment, followed by prostate cancer.
For Olympus, the investment marks a return to a category where its first major bet did not play out as planned.
The Numbers
Compass AI has logged 12 prostate and urology device financings since 1 August 2025. Ten closed deals with disclosed values totaled $313.6 million, alongside Sonablate’s financing commitment of up to $200 million and one undisclosed round.
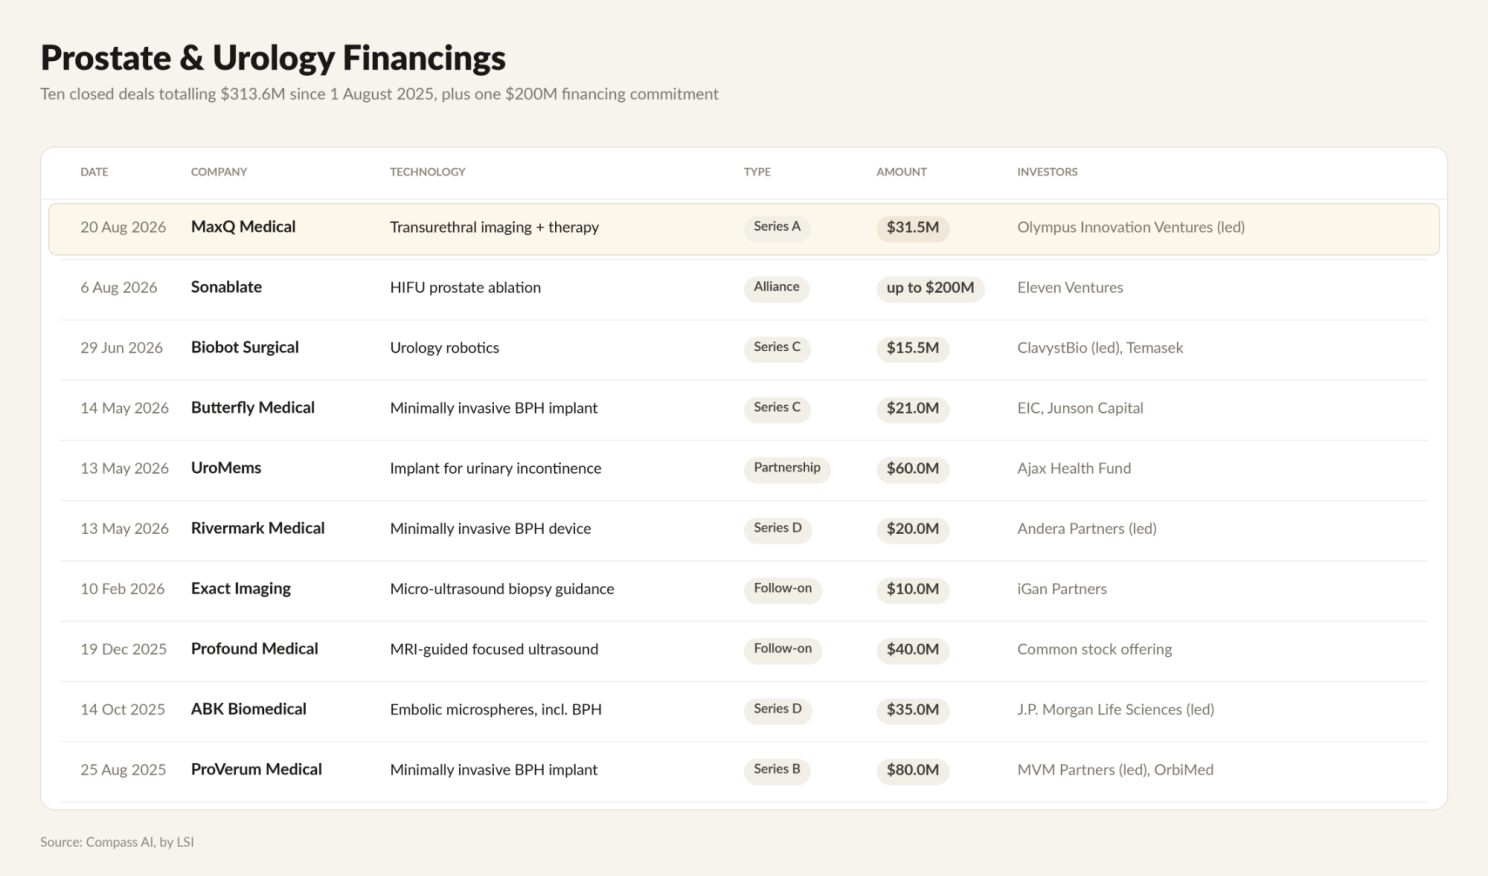
The underlying market is substantial. Roughly 40 million American men have BPH, and the BPH surgical treatment market was valued at $12.62 billion in 2024. It is projected to reach $17.19 billion by 2030, representing a 5.3% CAGR.
Three years ago, plenty of people had written off this large, slow-moving market. What happened next changed its trajectory.
How the Previous Model Broke
Teleflex agreed to acquire NeoTract, maker of UroLift, in September 2017 for $725 million upfront and as much as $1.1 billion including milestones. The strategy centered on moving procedures out of hospitals and into urology offices, where higher procedure volumes could support the economics.
Olympus followed a similar path in February 2021, exercising its call option on Israel-based Medi-Tate and acquiring the iTind implant for $300 million. The non-surgical device was designed for an in-office procedure, with the nitinol implant remaining in place for five to seven days.
Then reimbursement changed.
Office-site reimbursement was cut across more than 600 office-based procedures, UroLift among them, by 8% and 11% in year one, phased over four years beginning in 2022. The economics behind the office-based model shifted with them.
By December 2025, Teleflex announced plans to divest three businesses for $2.03 billion. UroLift was included in a $530 million transaction with the company’s acute care business, sold to British respiratory device manufacturer Intersurgical. The OEM portion of the transaction closed on 3 August 2026.
The New BPH Treatment Model
As reimbursement challenged the office-based approach, PROCEPT BioRobotics was scaling a capital equipment model.
For Q2 2026, PROCEPT reported $94.5 million in revenue, up 19%, including $83.4 million in U.S. revenue, up 20%. More than 13,100 U.S. Aquablation procedures were performed during the quarter, an increase of roughly 21%.
The company also placed 65 HYDROS systems in the U.S., including 50 at greenfield sites, with a record greenfield average selling price of $495,000. Gross margin reached 66%, while full-year revenue guidance remained $390 million to $410 million compared with $325.5 million in FY2025.
The model pairs hospital and ASC capital equipment with recurring handpiece revenue from each procedure. With procedure growth exceeding revenue growth, utilization per installed system is continuing to rise.
Boston Scientific is pushing further into the same market. Rezūm’s clearance was expanded this year from prostates of 30 to 80cc to prostates up to 150cc, bringing it into large-gland territory where Aquablation has been strongest.
Why Olympus Is Trying Again
Olympus already owns a critical part of transurethral access. More than 60% of its revenue comes from Endoscopic Solutions, and the resectoscope has supported BPH surgery for decades.
But the access-point market is valued at $458 million in 2026 and is growing slowly. More value has shifted toward therapeutic modalities and the imaging used to guide them.
MaxQ gives Olympus a different route into that opportunity. Instead of another implant dependent on office-based reimbursement, the company is backing an integrated imaging and therapy platform that starts with BPH and could expand into prostate cancer.
Other companies are pursuing the same overlap between benign disease and oncology. Sonablate, Profound Medical, Exact Imaging, and Focal Medical Technology are all positioned around that boundary.
$31.5 million is a cheap option on that. It is one-tenth of what Olympus paid for iTind.
What We’re Watching
First, watch whether Olympus moves from investor to acquirer. Co-leading the Series A resembles the venture-stake-before-premium pattern seen when Medtronic co-led RapidPulse in July. Olympus has previously progressed from investment to acquisition within four years, making a MaxQ Series B worth watching.
ProVerum, Rivermark, and Butterfly are another test. Together, the three implant companies have raised more than $120 million since August 2025. Compass AI also lists an unnamed strategic investor in Rivermark’s May financing.
Then there is UroLift. Intersurgical now owns the BPH franchise. Investment could give the office-based model another chapter, while a harvest strategy would strengthen the case that the market has shifted toward capital equipment.
Finally, PROCEPT’s utilization will be one to watch. Procedures grew 21% in Q2 while revenue increased 19%. If that trajectory continues, the upper end of its $390 million to $410 million guidance could prove conservative.
Olympus’ return to BPH treatment is not a repeat of its first bet. This time, it is backing imaging, therapy, and a potential path from benign disease into oncology, while the broader market tests which business model will define the next cycle.

Request Info

The Lens - Complimentary Issue
Subscription Includes

Global Medtech Market Analysis & Projections (MAP), 2021-2031
Published: 2023
Next Update: Q4 2024
Deliverables:


Global Surgical Procedure Volumes Dashboard, 2018-2029
Published: 2022
Next Update: Q2 2024
Deliverables:
United States Surgical Procedure Volumes, 2018-2029
Published: 2022
Next Update: Q2 2024
Deliverables:
Aesthetics, Global Surgical Procedure Volumes, 2018-2029
Published: 2022
Next Update: Q2 2024
Deliverables:
Cardio, Global Surgical Procedure Volumes, 2018-2029
Published: 2022
Next Update: Q2 2024
Deliverables:
ENT, Global Surgical Procedure Volumes, 2018-2029
Published: 2022
Next Update: Q2 2024
Deliverables:
General, Global Surgical Procedure Volumes, 2018-2029
Published: 2022
Next Update: Q2 2024
Deliverables:
Neuro, Global Surgical Procedure Volumes, 2018-2029
Published: 2022
Next Update: Q2 2024
Deliverables:
OB/GYN, Global Surgical Procedure Volumes, 2018-2029
Published: 2022
Next Update: Q2 2024
Deliverables:
Ophthalmology, Global Surgical Procedure Volumes, 2018-2029
Published: 2022
Next Update: Q2 2024
Deliverables:
Orthopedic, Global Surgical Procedure Volumes, 2018-2029
Published: 2022
Next Update: Q2 2024
Deliverables:
Peripheral Vascular, Global Surgical Procedure Volumes, 2018-2029
Published: 2022
Next Update: Q2 2024
Deliverables:
Spine, Global Surgical Procedure Volumes, 2018-2029
Published: 2022
Next Update: Q2 2024
Deliverables:
SRS, Global Surgical Procedure Volumes, 2018-2029
Published: 2022
Next Update: Q2 2024
Deliverables:
Urological, Global Surgical Procedure Volumes, 2018-2029
Published: 2022
Next Update: Q2 2024
Deliverables:
Global Markets for Hip Replacement Implants, 2023-2028
Published: 2023
Next Update: Q2 2024
Deliverables:
Global Markets for Peripheral Vascular Guidewires, 2023-2028
Published: 2023
Next Update: Q2 2024
Deliverables:
Global Markets for Peripheral Atherectomy Catheters, 2023-2028
Published: 2023
Next Update: Q2 2024
Deliverables:
Global Markets for Electrosurgery, 2023-2028
Published: 2023
Next Update: Q2 2024
Deliverables:
Global Markets for Peripheral Vascular Balloons & Vena Cava Filter, 2023-2028
Published: 2023
Next Update: Q2 2024
Deliverables:
Global Markets for Mechanical Heart Valves, 2023-2028
Published: 2023
Next Update: Q2 2024
Deliverables:
Global Markets for Tissue Heart Valve Replacement, 2023-2028
Published: 2023
Next Update: Q2 2030
Deliverables:
Global Markets for Transcatheter Mitral Valve Devices, 2023-2028
Published: 2023
Next Update: Q2 2024
Deliverables:
Global Markets for Femoral Closure, 2023-2029
Published: 2023
Next Update: Q2 2024
Deliverables:
Global Markets for Tricuspid Valve Repair, 2023-2028
Published: 2023
Next Update: Q2 2024
Deliverables:
Global Markets for Percutaneous Pulmonary Valves, 2023-2028
Published: 2023
Next Update: Q2 2024
Deliverables:
Global Markets for Coronary Angio Guidewires & Catheters, 2023-2028
Published: 2023
Next Update: Q2 2024
Deliverables:
Global Markets for Oncology Ablation Devices, 2023-2028
Published: 2023
Next Update: Q2 2024
Deliverables:
Global Markets for ENT Devices, 2023-2028
Published: 2023
Next Update: Q2 2024
Deliverables:
Global Markets for Cell Delivery Catheters, 2023-2028
Published: 2023
Next Update: Q3 2024
Deliverables:
Global Markets for Urology Devices, 2023-2028
Published: 2023
Next Update: Q3 2024
Deliverables:
Global Markets for External Pain Pumps, 2023-2028
Published: 2023
Next Update: Q3 2024
Deliverables:
Global Markets for Ureteral Access Devices, 2023-2028
Published: 2023
Next Update: Q3 2024
Deliverables:
Global Markets for Pelvic Floor Repair, 2023-2028
Published: 2023
Next Update: Q3 2024
Deliverables:
Global Markets for Atrial Fibrillation, 2023-2028
Published: 2023
Next Update: Q3 2024
Deliverables:
Global Markets for Neurovascular Devices Ischemic, 2023-2028
Published: 2023
Next Update: Q3 2024
Deliverables:
Global Markets for Neuromodulation Devices, 2023-2028
Published: 2023
Next Update: Q3 2024
Deliverables:
Global Markets for Vertebroplasty Devices, 2023-2028
Published: 2023
Next Update: Q3 2024
Deliverables:
Global Markets for Benign Prostation Hyperplasia Implants, 2023-2028
Published: 2023
Next Update: Q3 2024
Deliverables:
Global Markets for Cryoablation, 2023-2028
Published: 2023
Next Update: Q3 2024
Deliverables:
Global Markets for Diagnostic Electrophysiology Catheters, 2023-2028
Published: 2023
Next Update: Q3 2024
Deliverables:
Global Markets for Hernia Repair, 2023-2028
Published: 2023
Next Update: Q4 2024
Deliverables:
Global Markets for CRM Devices, 2023-2028
Published: 2023
Next Update: Q4 2024
Deliverables:
Global Markets for Neurovascular Devices Hemorrhagic, 2023-2028
Published: 2023
Next Update: Q4 2024
Deliverables:
Global Markets for Renal Denervation, 2023-2028
Published: 2023
Next Update: Q4 2024
Deliverables:
Global Markets for Upper+Lower Suture Anchors, 2023-2028
Published: 2023
Next Update: Q4 2024
Deliverables:
Global Markets for Peripheral Stents, 2023-2028
Published: 2023
Next Update: Q4 2024
Deliverables:
Global Markets for Electromagnetic Navigation Systems, 2023-2028
Published: 2023
Next Update: Q4 2024
Deliverables:
Global Markets for GI Endoscopy, 2023-2028
Published: 2023
Next Update: Q4 2024
Deliverables:
Global Markets for Hemodialysis, 2023-2028
Published: 2023
Next Update: Q4 2024
Deliverables:
Globals Markets for Cardiac Ablation, 2023-2028
Published:
Next Update:
Deliverables:
Global Markets for Atrial Septal Occlusion, 2023-2028
Published: 2023
Next Update: Q4 2024
Deliverables:
Global Markets for Aortic Grafts, 2023-2028
Published: 2023
Next Update: Q4 2024
Deliverables:
Global Markets for Interventional Cardiology Devices, 2023-2028
Published: 2023
Next Update: Q4 2024
Deliverables:
Global Markets for Oncology Embolization, 2023-2028
Published: 2023
Next Update: Q4 2024
Deliverables:
Global Markets for Vascular Access Devices, 2023-2028
Published: 2023
Next Update: Q4 2024
Deliverables:
Global Markets for Rotator Cuff Repair Suture Anchors, 2023-2028
Published: 2023
Next Update: Q4 2024
Deliverables:
Global Markets for Electrical Stimulation Devices, 2023-2028
Published: 2023
Next Update: Q4 2024
Deliverables:
Global Markets for Wearable Monitoring Devices, 2023-2028
Published: 2023
Next Update: Q4 2024
Deliverables:
Global Markets for Low Complexity Medical Devices, 2023-2028
Published: 2023
Next Update: Q4 2024
Deliverables:
Canada Surgical Procedure Volumes, 2018-2029
Published: 2022
Next Update: Q2 2024
Deliverables:
Germany Surgical Procedure Volumes, 2018-2029
Published: 2022
Next Update: Q2 2024
Deliverables:
France Surgical Procedure Volumes, 2018-2029
Published: 2022
Next Update: Q2 2024
Deliverables:
U.K. Surgical Procedure Volumes, 2018-2029
Published: 2022
Next Update: Q2 2024
Deliverables:
Italy Surgical Procedure Volumes, 2018-2029
Published: 2022
Next Update: Q2 2024
Deliverables:
Spain Surgical Procedure Volumes, 2018-2029
Published: 2022
Next Update: Q2 2024
Deliverables:
Poland Surgical Procedure Volumes, 2018-2029
Published: 2022
Next Update: Q2 2024
Deliverables:
Netherlands Surgical Procedure Volumes, 2018-2029
Published: 2022
Next Update: Q2 2024
Deliverables:
Belgium Surgical Procedure Volumes, 2018-2029
Published: 2022
Next Update: Q2 2024
Deliverables:
Sweden Surgical Procedure Volumes, 2018-2029
Published: 2022
Next Update: Q2 2024
Deliverables:
Switzerland Surgical Procedure Volumes, 2018-2029
Published: 2022
Next Update: Q2 2024
Deliverables:
Denmark Surgical Procedure Volumes, 2018-2029
Published: 2022
Next Update: Q2 2024
Deliverables:
Finland Surgical Procedure Volumes, 2018-2029
Published: 2022
Next Update: Q2 2024
Deliverables:
Norway Surgical Procedure Volumes, 2018-2029
Published: 2022
Next Update: Q2 2024
Deliverables:
China Surgical Procedure Volumes, 2018-2029
Published: 2022
Next Update: Q2 2024
Deliverables:
India Surgical Procedure Volumes, 2018-2029
Published: 2022
Next Update: Q2 2024
Deliverables:
Japan Surgical Procedure Volumes, 2018-2029
Published: 2022
Next Update: Q2 2024
Deliverables:
South Korea Surgical Procedure Volumes, 2018-2029
Published: 2022
Next Update: Q2 2024
Deliverables:
Australia Surgical Procedure Volumes, 2018-2029
Published: 2022
Next Update: Q2 2024
Deliverables:
Thailand Surgical Procedure Volumes, 2018-2029
Published: 2022
Next Update: Q2 2024
Deliverables:
Malaysia Surgical Procedure Volumes, 2018-2029
Published: 2022
Next Update: Q2 2024
Deliverables:
Singapore Surgical Procedure Volumes, 2018-2029
Published: 2022
Next Update: Q2 2024
Deliverables:
New Zealand Surgical Procedure Volumes, 2018-2029
Published: 2022
Next Update: Q2 2024
Deliverables:
Caribbean Surgical Procedure Volumes, 2018-2029
Published: 2022
Next Update: Q2 2024
Deliverables:
Argentina Surgical Procedure Volumes, 2018-2029
Published: 2022
Next Update: Q2 2024
Deliverables:
Colombia Surgical Procedure Volumes, 2018-2029
Published: 2022
Next Update: Q2 2024
Deliverables:
Chile Surgical Procedure Volumes, 2018-2029
Published: 2022
Next Update: Q2 2024
Deliverables:
Guatemala Surgical Procedure Volumes, 2018-2029
Published: 2022
Next Update: Q2 2024
Deliverables:
Dominican Republic Surgical Procedure Volumes, 2018-2029
Published: 2022
Next Update: Q2 2024
Deliverables:
Costa Rica Surgical Procedure Volumes, 2018-2029
Published: 2022
Next Update: Q2 2024
Deliverables:
Panama Surgical Procedure Volumes, 2018-2029
Published: 2022
Next Update: Q2 2024
Deliverables:
Mexico Surgical Procedure Volumes, 2018-2029
Published: 2022
Next Update: Q2 2024
Deliverables:
Brazil Surgical Procedure Volumes, 2018-2029
Published: 2022
Next Update: Q2 2024
Deliverables:
Turkey Surgical Procedure Volumes, 2018-2029
Published: 2022
Next Update: Q2 2024
Deliverables:
Russia Surgical Procedure Volumes, 2018-2029
Published: 2022
Next Update: Q2 2024
Deliverables:
South Africa Surgical Procedure Volumes, 2018-2029
Published: 2022
Next Update: Q2 2024
Deliverables:
Request Info
See Full Attendee List