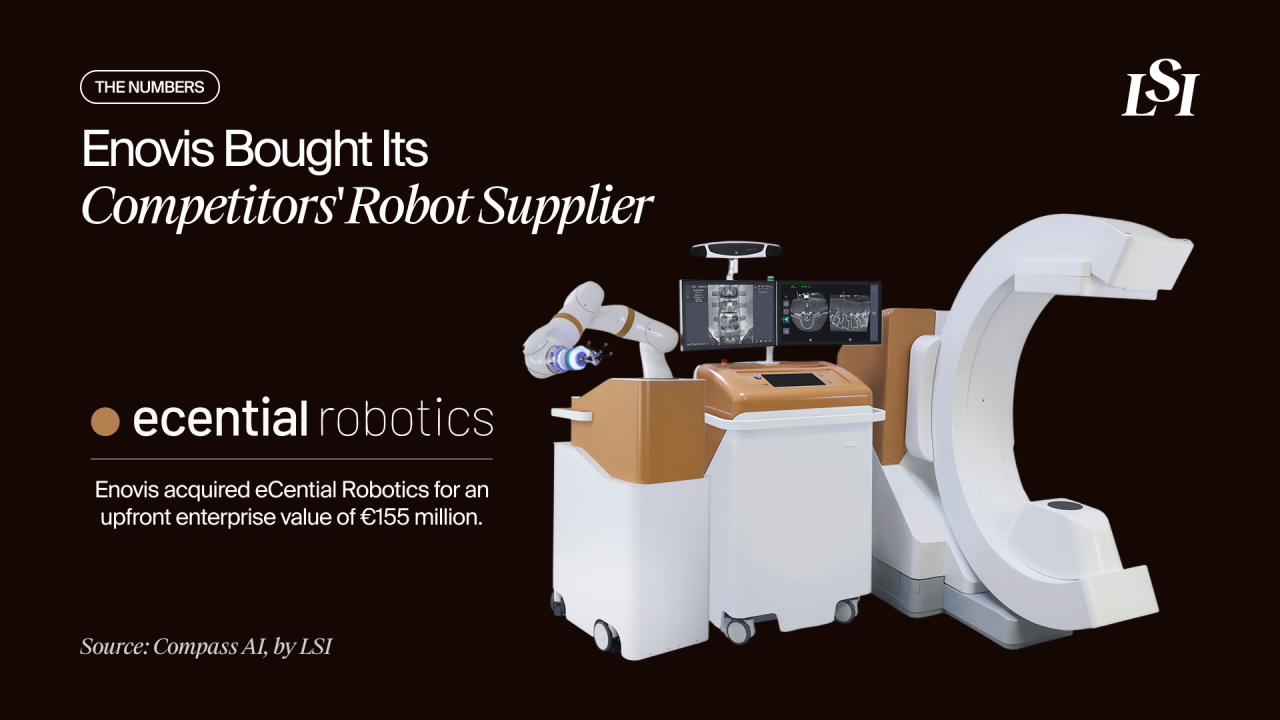
Enovis is filling one of the biggest gaps in its reconstructive portfolio.
On September 1, the company made a binding offer to acquire LSI Alumni company eCential Robotics for €155 million upfront, plus up to €35 million in potential milestones. That works out to roughly $180 million at closing and as much as €190 million in total consideration. The transaction is expected to close during the fourth quarter of 2026, subject to regulatory approvals.
For Enovis, the acquisition provides a path into orthopedic robots. But eCential brings something more unusual than a single robotic system. It has spent years building technology for other orthopedic companies, including some that will soon compete directly with its new owner.
The Numbers Behind the Deal
eCential was founded in 2009 and raised approximately €100 million through equity, quasi-equity, and debt in January 2021. Across six rounds, the company raised roughly $110 million over its lifetime.
Enovis is now offering €155 million upfront, with the potential for the transaction to reach €190 million.
The price also looks familiar.
Zimmer Biomet acquired Monogram Technologies for $177 million in July 2025. 14 months later, Enovis agreed to pay roughly $180 million upfront for eCential. The two independent robotics companies landed within about 2% of each other.
Meanwhile, the scale of the established competition continues to grow. Stryker had installed 3,000 Mako systems by year-end 2025. More than two-thirds of its U.S. knee procedures and more than one-third of its U.S. hip procedures use Mako, while more than half of knee procedures globally are now robot-assisted.
Enovis expects its own knee robot to launch in late 2028, followed by a shoulder system in 2029, with initial commercial contribution beginning in 2028.
Enovis guides to $2.31 billion to $2.37 billion in 2026 revenue. Q2 revenue reached $582.8 million, up 3% reported. The stock fell about 9% on that print on August 6. Four weeks later, management committed $180 million to a product that ships in 26 months.
What Enovis Gets With eCential
The unusual part of the acquisition is eCential’s position as an implant-agnostic robotics company.
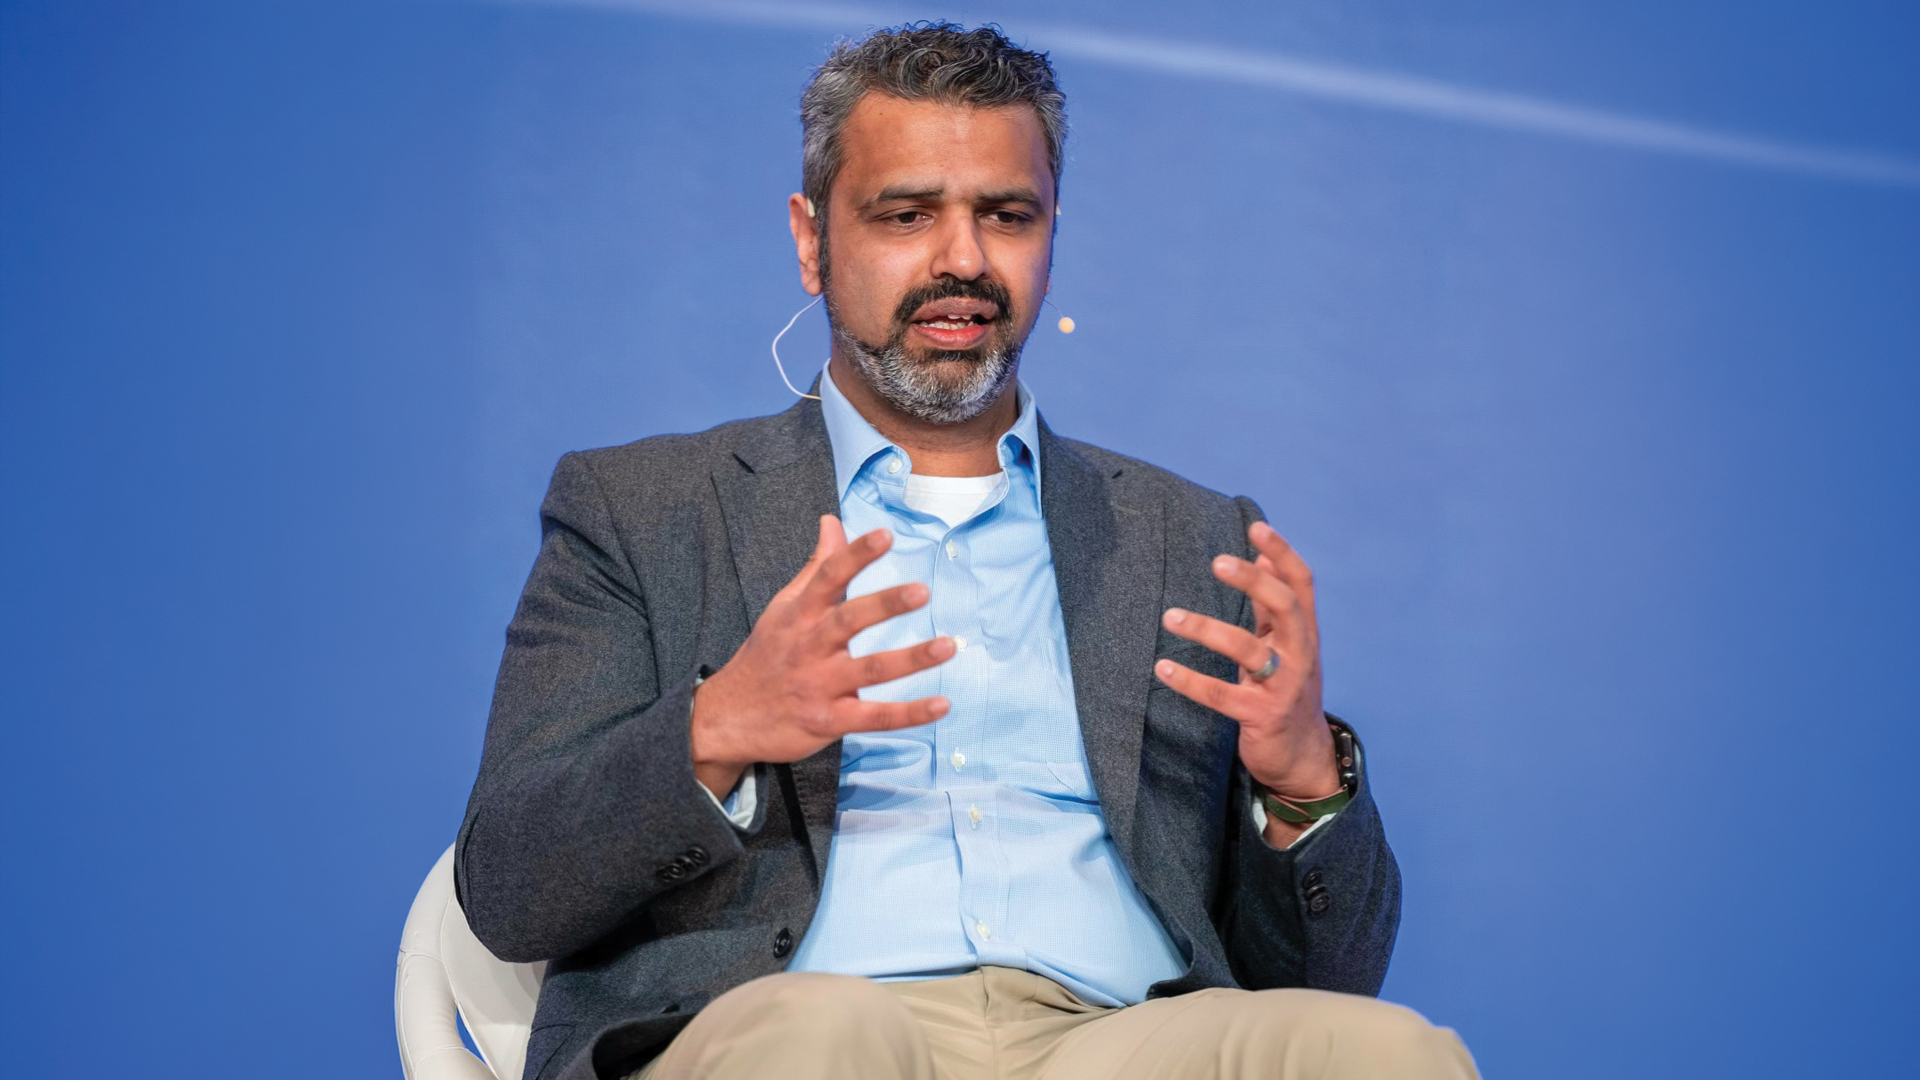
At LSI USA ’26, CEO Clément Vidal described the company simply: “We are not an implant manufacturer; our platform is implant agnostic.”
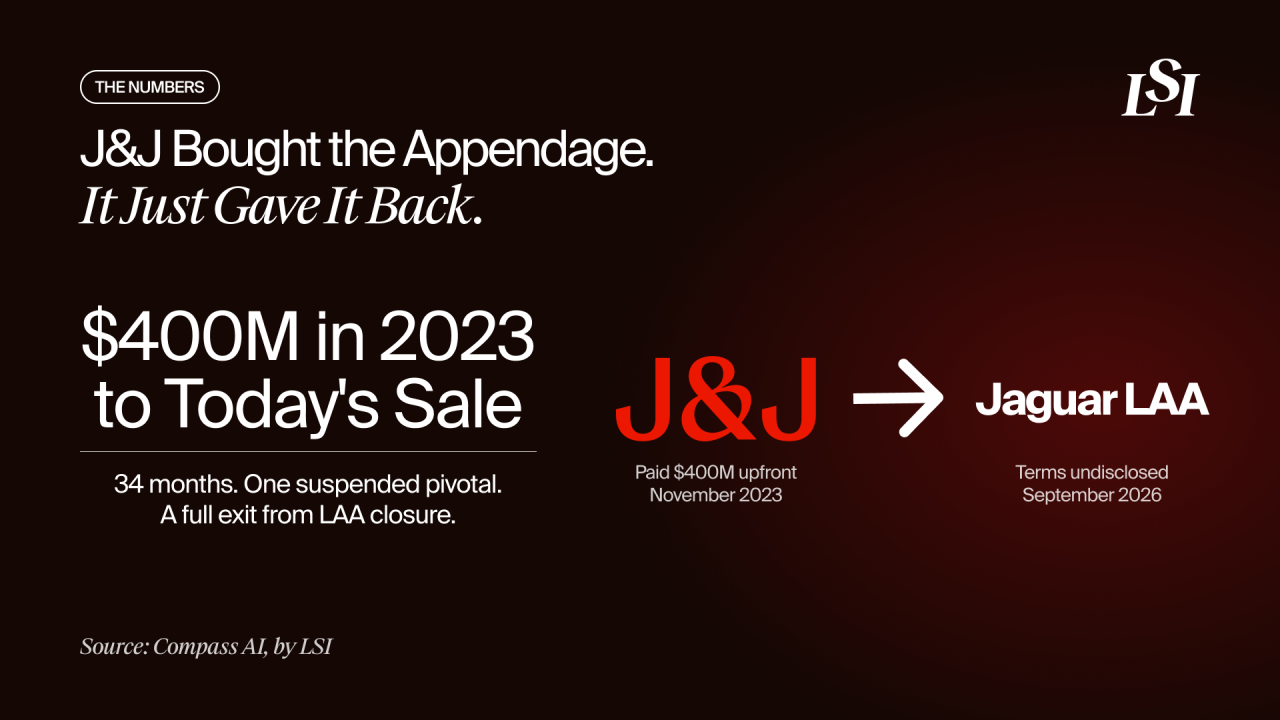
That approach created several businesses. eCential developed the VELYS Spine robot for J&J MedTech’s DePuy Synthes “from specification to FDA clearance on behalf of J&J,” according to Vidal. VELYS Spine received FDA clearance in 2024, launched commercially in the first half of 2025, and surpassed 600 cases by March 2026.
eCential also supplies its robotic platform through a non-exclusive OEM agreement for Amplitude Surgical’s Andy knee robot, which received CE marking in November 2025. Amplitude is now owned by India-based Zydus Lifesciences.
Then there is eCential’s own Op.n platform, an implant-agnostic system that recently received FDA clearance and entered a limited U.S. release.
Enovis has said it intends to maintain eCential’s existing partnerships and establish a robotics center of excellence in Grenoble. It also says it does not plan to enter surgical spine. Its own robotics roadmap instead begins with total knee and moves into total shoulder.
The Market for Independent Orthopedic Robots
The acquisition arrives as robotics increasingly shapes the competitive structure of orthopedics.
Stryker has Mako. Zimmer Biomet has ROSA and Monogram. J&J has VELYS, whose spine system was developed by eCential. Enovis is now spending roughly $180 million to close what BTIG described as its “most notable competitive gap.”
There are also signs that independent robotics companies are becoming acquisition targets. Monogram has been acquired. eCential is under agreement to be acquired. THINK Surgical raised $100 million from KDB in October 2022 and secured a $15 million debt facility with milestone tranches in July 2026.
The question now is what happens to eCential’s open-platform model inside an implant manufacturer.
Amplitude and Zydus will have to decide whether to maintain their OEM relationship once Enovis launches a competing knee robot. Enovis will also need to retain eCential’s engineering expertise through the integration while preparing its knee and shoulder systems for market.
Six months before the acquisition announcement, Vidal closed his LSI USA ’26 presentation by telling the audience that eCential was not raising capital but welcomed discussions with “industrial or strategics” interested in developing new robotic applications in bone surgery.
By September, one of those strategics had made its move.

Request Info

The Lens - Complimentary Issue
Subscription Includes

Global Medtech Market Analysis & Projections (MAP), 2021-2031
Published: 2023
Next Update: Q4 2024
Deliverables:


Global Surgical Procedure Volumes Dashboard, 2018-2029
Published: 2022
Next Update: Q2 2024
Deliverables:
United States Surgical Procedure Volumes, 2018-2029
Published: 2022
Next Update: Q2 2024
Deliverables:
Aesthetics, Global Surgical Procedure Volumes, 2018-2029
Published: 2022
Next Update: Q2 2024
Deliverables:
Cardio, Global Surgical Procedure Volumes, 2018-2029
Published: 2022
Next Update: Q2 2024
Deliverables:
ENT, Global Surgical Procedure Volumes, 2018-2029
Published: 2022
Next Update: Q2 2024
Deliverables:
General, Global Surgical Procedure Volumes, 2018-2029
Published: 2022
Next Update: Q2 2024
Deliverables:
Neuro, Global Surgical Procedure Volumes, 2018-2029
Published: 2022
Next Update: Q2 2024
Deliverables:
OB/GYN, Global Surgical Procedure Volumes, 2018-2029
Published: 2022
Next Update: Q2 2024
Deliverables:
Ophthalmology, Global Surgical Procedure Volumes, 2018-2029
Published: 2022
Next Update: Q2 2024
Deliverables:
Orthopedic, Global Surgical Procedure Volumes, 2018-2029
Published: 2022
Next Update: Q2 2024
Deliverables:
Peripheral Vascular, Global Surgical Procedure Volumes, 2018-2029
Published: 2022
Next Update: Q2 2024
Deliverables:
Spine, Global Surgical Procedure Volumes, 2018-2029
Published: 2022
Next Update: Q2 2024
Deliverables:
SRS, Global Surgical Procedure Volumes, 2018-2029
Published: 2022
Next Update: Q2 2024
Deliverables:
Urological, Global Surgical Procedure Volumes, 2018-2029
Published: 2022
Next Update: Q2 2024
Deliverables:
Global Markets for Hip Replacement Implants, 2023-2028
Published: 2023
Next Update: Q2 2024
Deliverables:
Global Markets for Peripheral Vascular Guidewires, 2023-2028
Published: 2023
Next Update: Q2 2024
Deliverables:
Global Markets for Peripheral Atherectomy Catheters, 2023-2028
Published: 2023
Next Update: Q2 2024
Deliverables:
Global Markets for Electrosurgery, 2023-2028
Published: 2023
Next Update: Q2 2024
Deliverables:
Global Markets for Peripheral Vascular Balloons & Vena Cava Filter, 2023-2028
Published: 2023
Next Update: Q2 2024
Deliverables:
Global Markets for Mechanical Heart Valves, 2023-2028
Published: 2023
Next Update: Q2 2024
Deliverables:
Global Markets for Tissue Heart Valve Replacement, 2023-2028
Published: 2023
Next Update: Q2 2030
Deliverables:
Global Markets for Transcatheter Mitral Valve Devices, 2023-2028
Published: 2023
Next Update: Q2 2024
Deliverables:
Global Markets for Femoral Closure, 2023-2029
Published: 2023
Next Update: Q2 2024
Deliverables:
Global Markets for Tricuspid Valve Repair, 2023-2028
Published: 2023
Next Update: Q2 2024
Deliverables:
Global Markets for Percutaneous Pulmonary Valves, 2023-2028
Published: 2023
Next Update: Q2 2024
Deliverables:
Global Markets for Coronary Angio Guidewires & Catheters, 2023-2028
Published: 2023
Next Update: Q2 2024
Deliverables:
Global Markets for Oncology Ablation Devices, 2023-2028
Published: 2023
Next Update: Q2 2024
Deliverables:
Global Markets for ENT Devices, 2023-2028
Published: 2023
Next Update: Q2 2024
Deliverables:
Global Markets for Cell Delivery Catheters, 2023-2028
Published: 2023
Next Update: Q3 2024
Deliverables:
Global Markets for Urology Devices, 2023-2028
Published: 2023
Next Update: Q3 2024
Deliverables:
Global Markets for External Pain Pumps, 2023-2028
Published: 2023
Next Update: Q3 2024
Deliverables:
Global Markets for Ureteral Access Devices, 2023-2028
Published: 2023
Next Update: Q3 2024
Deliverables:
Global Markets for Pelvic Floor Repair, 2023-2028
Published: 2023
Next Update: Q3 2024
Deliverables:
Global Markets for Atrial Fibrillation, 2023-2028
Published: 2023
Next Update: Q3 2024
Deliverables:
Global Markets for Neurovascular Devices Ischemic, 2023-2028
Published: 2023
Next Update: Q3 2024
Deliverables:
Global Markets for Neuromodulation Devices, 2023-2028
Published: 2023
Next Update: Q3 2024
Deliverables:
Global Markets for Vertebroplasty Devices, 2023-2028
Published: 2023
Next Update: Q3 2024
Deliverables:
Global Markets for Benign Prostation Hyperplasia Implants, 2023-2028
Published: 2023
Next Update: Q3 2024
Deliverables:
Global Markets for Cryoablation, 2023-2028
Published: 2023
Next Update: Q3 2024
Deliverables:
Global Markets for Diagnostic Electrophysiology Catheters, 2023-2028
Published: 2023
Next Update: Q3 2024
Deliverables:
Global Markets for Hernia Repair, 2023-2028
Published: 2023
Next Update: Q4 2024
Deliverables:
Global Markets for CRM Devices, 2023-2028
Published: 2023
Next Update: Q4 2024
Deliverables:
Global Markets for Neurovascular Devices Hemorrhagic, 2023-2028
Published: 2023
Next Update: Q4 2024
Deliverables:
Global Markets for Renal Denervation, 2023-2028
Published: 2023
Next Update: Q4 2024
Deliverables:
Global Markets for Upper+Lower Suture Anchors, 2023-2028
Published: 2023
Next Update: Q4 2024
Deliverables:
Global Markets for Peripheral Stents, 2023-2028
Published: 2023
Next Update: Q4 2024
Deliverables:
Global Markets for Electromagnetic Navigation Systems, 2023-2028
Published: 2023
Next Update: Q4 2024
Deliverables:
Global Markets for GI Endoscopy, 2023-2028
Published: 2023
Next Update: Q4 2024
Deliverables:
Global Markets for Hemodialysis, 2023-2028
Published: 2023
Next Update: Q4 2024
Deliverables:
Globals Markets for Cardiac Ablation, 2023-2028
Published:
Next Update:
Deliverables:
Global Markets for Atrial Septal Occlusion, 2023-2028
Published: 2023
Next Update: Q4 2024
Deliverables:
Global Markets for Aortic Grafts, 2023-2028
Published: 2023
Next Update: Q4 2024
Deliverables:
Global Markets for Interventional Cardiology Devices, 2023-2028
Published: 2023
Next Update: Q4 2024
Deliverables:
Global Markets for Oncology Embolization, 2023-2028
Published: 2023
Next Update: Q4 2024
Deliverables:
Global Markets for Vascular Access Devices, 2023-2028
Published: 2023
Next Update: Q4 2024
Deliverables:
Global Markets for Rotator Cuff Repair Suture Anchors, 2023-2028
Published: 2023
Next Update: Q4 2024
Deliverables:
Global Markets for Electrical Stimulation Devices, 2023-2028
Published: 2023
Next Update: Q4 2024
Deliverables:
Global Markets for Wearable Monitoring Devices, 2023-2028
Published: 2023
Next Update: Q4 2024
Deliverables:
Global Markets for Low Complexity Medical Devices, 2023-2028
Published: 2023
Next Update: Q4 2024
Deliverables:
Canada Surgical Procedure Volumes, 2018-2029
Published: 2022
Next Update: Q2 2024
Deliverables:
Germany Surgical Procedure Volumes, 2018-2029
Published: 2022
Next Update: Q2 2024
Deliverables:
France Surgical Procedure Volumes, 2018-2029
Published: 2022
Next Update: Q2 2024
Deliverables:
U.K. Surgical Procedure Volumes, 2018-2029
Published: 2022
Next Update: Q2 2024
Deliverables:
Italy Surgical Procedure Volumes, 2018-2029
Published: 2022
Next Update: Q2 2024
Deliverables:
Spain Surgical Procedure Volumes, 2018-2029
Published: 2022
Next Update: Q2 2024
Deliverables:
Poland Surgical Procedure Volumes, 2018-2029
Published: 2022
Next Update: Q2 2024
Deliverables:
Netherlands Surgical Procedure Volumes, 2018-2029
Published: 2022
Next Update: Q2 2024
Deliverables:
Belgium Surgical Procedure Volumes, 2018-2029
Published: 2022
Next Update: Q2 2024
Deliverables:
Sweden Surgical Procedure Volumes, 2018-2029
Published: 2022
Next Update: Q2 2024
Deliverables:
Switzerland Surgical Procedure Volumes, 2018-2029
Published: 2022
Next Update: Q2 2024
Deliverables:
Denmark Surgical Procedure Volumes, 2018-2029
Published: 2022
Next Update: Q2 2024
Deliverables:
Finland Surgical Procedure Volumes, 2018-2029
Published: 2022
Next Update: Q2 2024
Deliverables:
Norway Surgical Procedure Volumes, 2018-2029
Published: 2022
Next Update: Q2 2024
Deliverables:
China Surgical Procedure Volumes, 2018-2029
Published: 2022
Next Update: Q2 2024
Deliverables:
India Surgical Procedure Volumes, 2018-2029
Published: 2022
Next Update: Q2 2024
Deliverables:
Japan Surgical Procedure Volumes, 2018-2029
Published: 2022
Next Update: Q2 2024
Deliverables:
South Korea Surgical Procedure Volumes, 2018-2029
Published: 2022
Next Update: Q2 2024
Deliverables:
Australia Surgical Procedure Volumes, 2018-2029
Published: 2022
Next Update: Q2 2024
Deliverables:
Thailand Surgical Procedure Volumes, 2018-2029
Published: 2022
Next Update: Q2 2024
Deliverables:
Malaysia Surgical Procedure Volumes, 2018-2029
Published: 2022
Next Update: Q2 2024
Deliverables:
Singapore Surgical Procedure Volumes, 2018-2029
Published: 2022
Next Update: Q2 2024
Deliverables:
New Zealand Surgical Procedure Volumes, 2018-2029
Published: 2022
Next Update: Q2 2024
Deliverables:
Caribbean Surgical Procedure Volumes, 2018-2029
Published: 2022
Next Update: Q2 2024
Deliverables:
Argentina Surgical Procedure Volumes, 2018-2029
Published: 2022
Next Update: Q2 2024
Deliverables:
Colombia Surgical Procedure Volumes, 2018-2029
Published: 2022
Next Update: Q2 2024
Deliverables:
Chile Surgical Procedure Volumes, 2018-2029
Published: 2022
Next Update: Q2 2024
Deliverables:
Guatemala Surgical Procedure Volumes, 2018-2029
Published: 2022
Next Update: Q2 2024
Deliverables:
Dominican Republic Surgical Procedure Volumes, 2018-2029
Published: 2022
Next Update: Q2 2024
Deliverables:
Costa Rica Surgical Procedure Volumes, 2018-2029
Published: 2022
Next Update: Q2 2024
Deliverables:
Panama Surgical Procedure Volumes, 2018-2029
Published: 2022
Next Update: Q2 2024
Deliverables:
Mexico Surgical Procedure Volumes, 2018-2029
Published: 2022
Next Update: Q2 2024
Deliverables:
Brazil Surgical Procedure Volumes, 2018-2029
Published: 2022
Next Update: Q2 2024
Deliverables:
Turkey Surgical Procedure Volumes, 2018-2029
Published: 2022
Next Update: Q2 2024
Deliverables:
Russia Surgical Procedure Volumes, 2018-2029
Published: 2022
Next Update: Q2 2024
Deliverables:
South Africa Surgical Procedure Volumes, 2018-2029
Published: 2022
Next Update: Q2 2024
Deliverables:
Request Info
See Full Attendee List